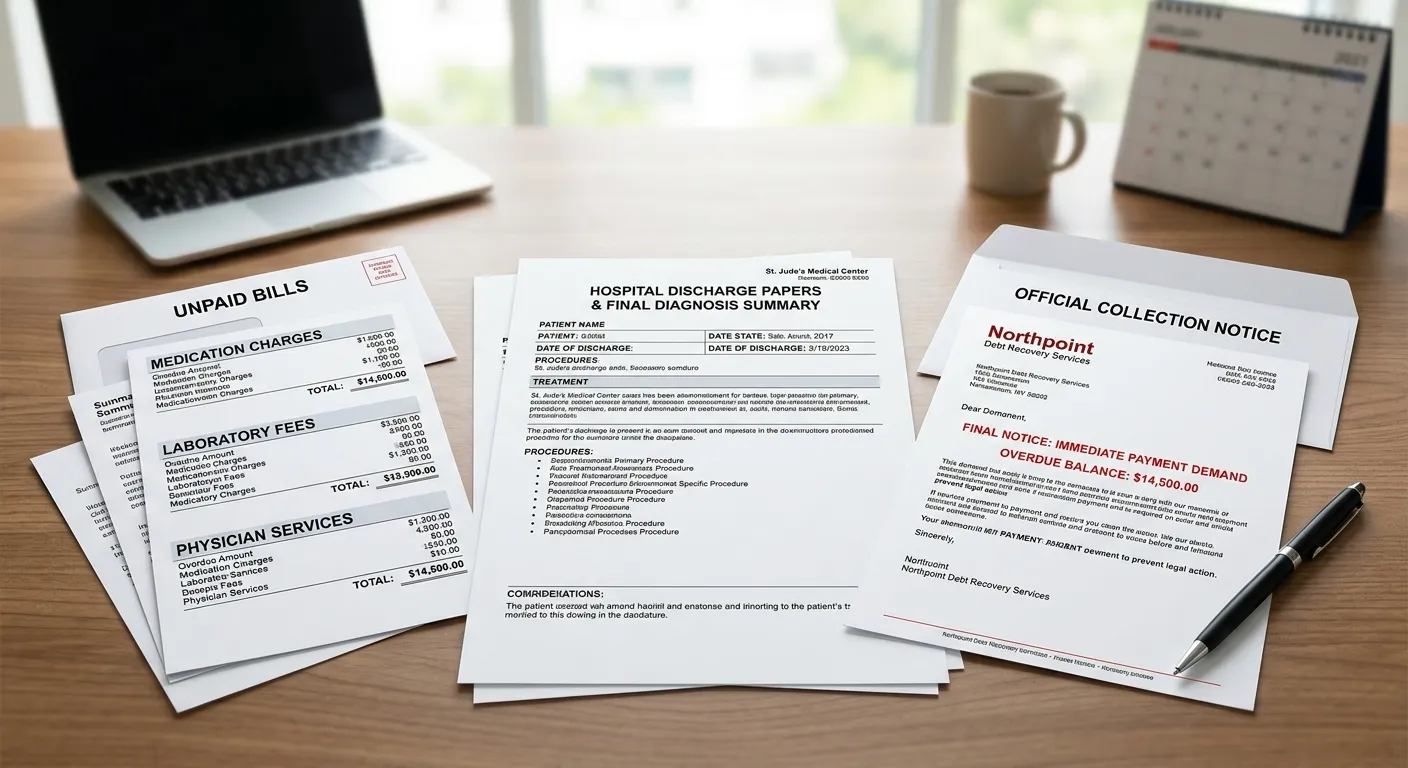
Experiencing a major health crisis alongside sudden unemployment creates immediate financial distress. Managing medical debt after job loss requires proactive debt validation strategies to prevent wage garnishments and credit score collapse.
When navigating medical debt after job loss, knowing your legal rights prevents collection agencies from taking advantage of your situation. Consequently, utilizing federal protection programs helps clear unpayable hospital bills while keeping essential living capital safe.
Stopping Collection Garnishments and Validating Debt
Collection agencies must obtain formal legal judgments before attempting to garnish wages or levy bank accounts. Sending formal written disputes halts collection activities while the debt’s validity undergoes verification.
- Demand Written Debt Verification: Mail a formal validation request via certified letter within thirty days of initial collection contact.
- Audit Hospital Billing Errors: Check hospital transfer statements for improper account assignments or incorrect billing codes.
- Stop Harassment Calls: Request written communications only to build a clear paper trail for potential legal disputes.
Hospital Charity Care and Tribal Assistance Programs
Non-profit hospitals must provide financial assistance programs under federal tax regulations. Applying for retroactive charity care waives outstanding medical balances for low-income patients.
Applying for Section 501r Relief
Federal policies require non-profit medical centers to adjust bill totals based on household earnings. Official health coverage guidelines from the U.S. Department of Health & Human Services detail how income-based financial assistance programs eliminate hospital balances for qualified patients.
Utilizing Tribal Protections
Members of federally recognized tribes can access Purchase and Referred Care (PRC) funds or hardship grants. Requesting retroactive authorization from tribal health administrators helps cover out-of-network emergency care costs.
Resolving Repossession Balances and Credit Card Debt
Lenders sell repossessed vehicles at wholesale auctions and bill borrowers for the remaining deficiency balance. Verifying legal repossession notices ensures lenders followed proper state auction procedures.
Checking Auto Repossession Notices
Request an itemized accounting of the repossession sale to verify fair market value calculations. Lenders who fail to issue proper legal notices lose the right to collect remaining deficiency balances in court.
Strategic Debt Settlement Versus Bankruptcy
Making partial payments on severely delinquent credit cards resets the legal statute of limitations for lawsuits. Evaluating Chapter 7 bankruptcy provides a complete discharge of medical bills, credit card balances, and auto deficiencies under immediate court protection.
Rebuilding Your Financial Security After Crisis
Recovering from severe disruptions requires structured debt resolution and steady income allocation. Securing legal protections restores financial stability while you rebuild long-term savings.
Building Strategic Emergency Protections
Establishing clear debt management priorities keeps basic living expenses safe during life transitions. Read our guide on how to build an emergency fund fast to secure liquid cash reserves. Learn about essential strategies to lower monthly bills to cut overhead, explore snowball vs avalanche debt payoff to tackle lingering balances, or review how to file for unemployment benefits to protect baseline income.
Disclaimer: The information provided on this website is for educational and informational purposes only and should not be construed as legal, tax, or financial advice.