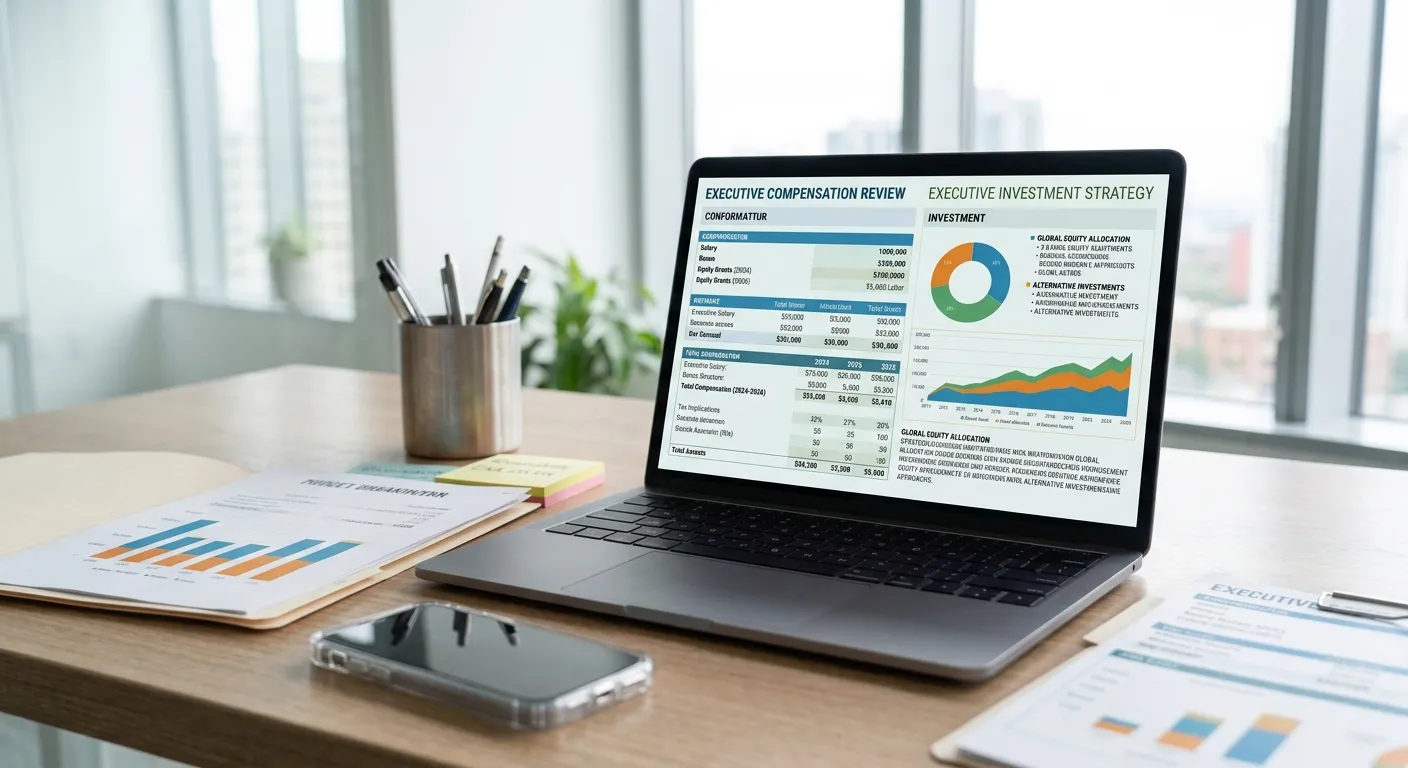
Receiving a dramatic executive compensation increase while moving to a lower-cost area creates a rare opportunity for rapid wealth accumulation. Managing a sudden jump in salary requires intentional planning to prevent lifestyle inflation from eroding long-term financial security.
Navigating a massive jump in salary involves creating automated saving systems before extra cash reaches your checking account. Consequently, committing your new compensation to structured investment vehicles secures your family’s future across generations.
Avoiding Lifestyle Creep and Managing Relocation Cash
Moving from a high-cost area to a lower-cost market significantly increases your effective discretionary cash flow. Resisting immediate luxury upgrades preserves capital for high-yield investment options.
- Anchor Living Expenses: Keep core household fixed overhead near your previous salary baseline to maximize monthly cash savings.
- Isolate One-Time Payouts: Direct sign-on bonuses and relocation stipends toward cash reserves or immediate tax obligations.
- Automate Savings Increases: Transfer new income surplus into brokerage accounts automatically on every payday.
Managing Restricted Stock Units and Variable Bonuses
Restricted Stock Units (RSUs) and large annual bonuses carry unique tax burdens and market concentration risks. Liquidating company shares upon vesting prevents your household net worth from tying heavily to a single employer.
RSU Diversification Strategies
Treat vested RSU shares as cash compensation and sell them immediately upon vesting to purchase broad-market index funds. Official investor education guides from the U.S. Securities and Exchange Commission highlight the importance of reducing single-stock concentration risk to protect long-term portfolio stability.
Tax Planning for Executive Bonuses
Supplemental wages like annual bonuses often face flat federal withholding rates that may fall short of your true marginal tax bracket. Consult a certified public accountant to adjust estimated tax payments and avoid underpayment penalties at year-end.
Catching Up on Retirement and Children’s College Funds
Starting aggressive retirement contributions at age 39 allows compound growth to rebuild your baseline portfolio rapidly. Diversifying across tax-advantaged accounts protects your wealth from future tax liabilities.
Maximize Tax-Advantage Accounts
Fully fund pre-tax 401k accounts, Backdoor Roth IRAs, and Health Savings Accounts (HSAs) before investing in taxable brokerage accounts. Maximizing these tax shelters accelerates your compound interest timeline.
Funding 529 College Savings Plans
Establish state-sponsored 529 plans for each child to secure tax-free growth for future higher education costs. Lump-sum contributions using initial bonus capital immediately establish a strong compounding foundation.
Securing Your Family’s Financial Future
Turning sudden income increases into lasting wealth requires discipline, proper asset allocation, and clear boundaries. Establishing automated investment habits keeps your family secure for decades to come.
Building Strategic Wealth Foundations
Maintaining strict allocation goals protects your capital as your career progresses. Read our guide on how to build an emergency fund fast to secure liquid cash. Learn about how to set up a 529 college plan to start saving for your children, explore essential low-risk investment strategies to grow wealth safely, or review how to manage variable bonus income to optimize annual payouts.
Disclaimer: The information provided on this website is for educational and informational purposes only and should not be construed as legal, tax, or financial advice.