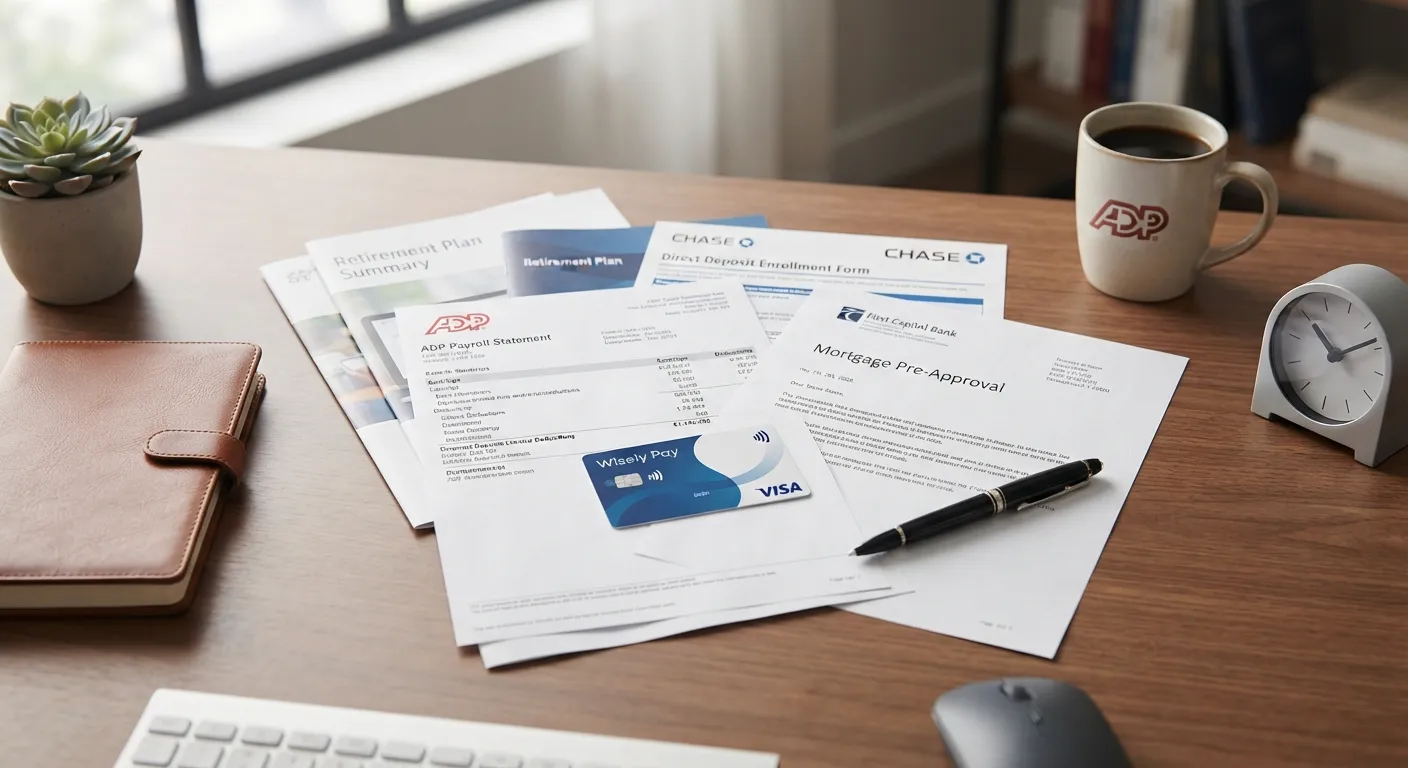
Using a Wisely pay card for your regular payroll distribution offers quick access to funds, but it introduces hidden financial risks. Treating a prepaid card like a standard bank account can leave you vulnerable during emergencies. When unexpected medical crises occur, rigid corporate policies can lock you out of your hard-earned funds.
If your employer relies on a Wisely pay card, establishing a traditional direct deposit to a real bank protects your financial security. To explore how major banking choices impact your long-term wealth, check out our guides on high-yield wealth building strategies for men and tips for spending money wisely. For official consumer banking rights, review resources from the Consumer Financial Protection Bureau.
Why a Wisely Pay Card Fails During Emergencies
Prepaid cards serve a purpose for immediate wage access. Still, they lack the robust customer support and legal flexibility of traditional financial institutions. When families face medical incapacitation or legal transitions, automated customer service scripts often fail to handle complex fiduciary situations.
Even when families present legally notarized power of attorney documents, prepaid card issuers frequently enforce strict verification roadblocks. This disconnect can trap thousands of dollars when you need liquidity the most. To manage your everyday cash flow safely, read our insights on daily budget impulse spending and best business tools for entrepreneurs.
The Advantages of Traditional Bank Accounts
Traditional banks and credit unions provide legal frameworks and human oversight that a Wisely pay card rarely matches. Opening a standard checking and savings account ensures you maintain full electronic transfer capabilities, branch access, and clear institutional accountability.
- Direct Access and Transfers: Traditional accounts allow seamless ACH transfers and wire payments to medical providers and utility companies.
- Fiduciary Recognition: Established banks possess dedicated legal compliance departments equipped to process power of attorney paperwork properly.
- Higher Balance Security: Standard accounts carry FDIC or NCUA insurance protection and offer comprehensive fraud monitoring tools.
Best Practices for Your Paycheck
Never leave large savings balances sitting on a prepaid payroll card. Withdraw or transfer your funds immediately after payday, and set up recurring transfers into a stable, traditional banking institution.
Disclaimer: The information provided on this website is for educational and informational purposes only and should not be construed as legal, tax, or financial advice.