Being quoted a 16 percent car loan APR with a strong 740 credit score comes as a massive shock. Shopping for a used car is an exciting milestone. Still, the financing stage creates a frustrating hurdle. You built a solid financial foundation. Seeing an extraordinarily high interest rate feels completely backward. Dealerships brush this off as normal. Yet, understanding your real value as a borrower protects you from paying thousands in extra interest.
You might encounter a 16 percent car loan APR despite having a clean credit history. Your instincts tell you the truth. You face an unfavorable deal. Major financing choices impact your broader financial picture. Structured wealth building matters. Read our guides on high-yield wealth building strategies for men and tips for spending money wisely. Check official consumer protections regarding auto loans from the Consumer Financial Protection Bureau.
Why a 16 Percent Car Loan APR Is Terrible for Good Credit
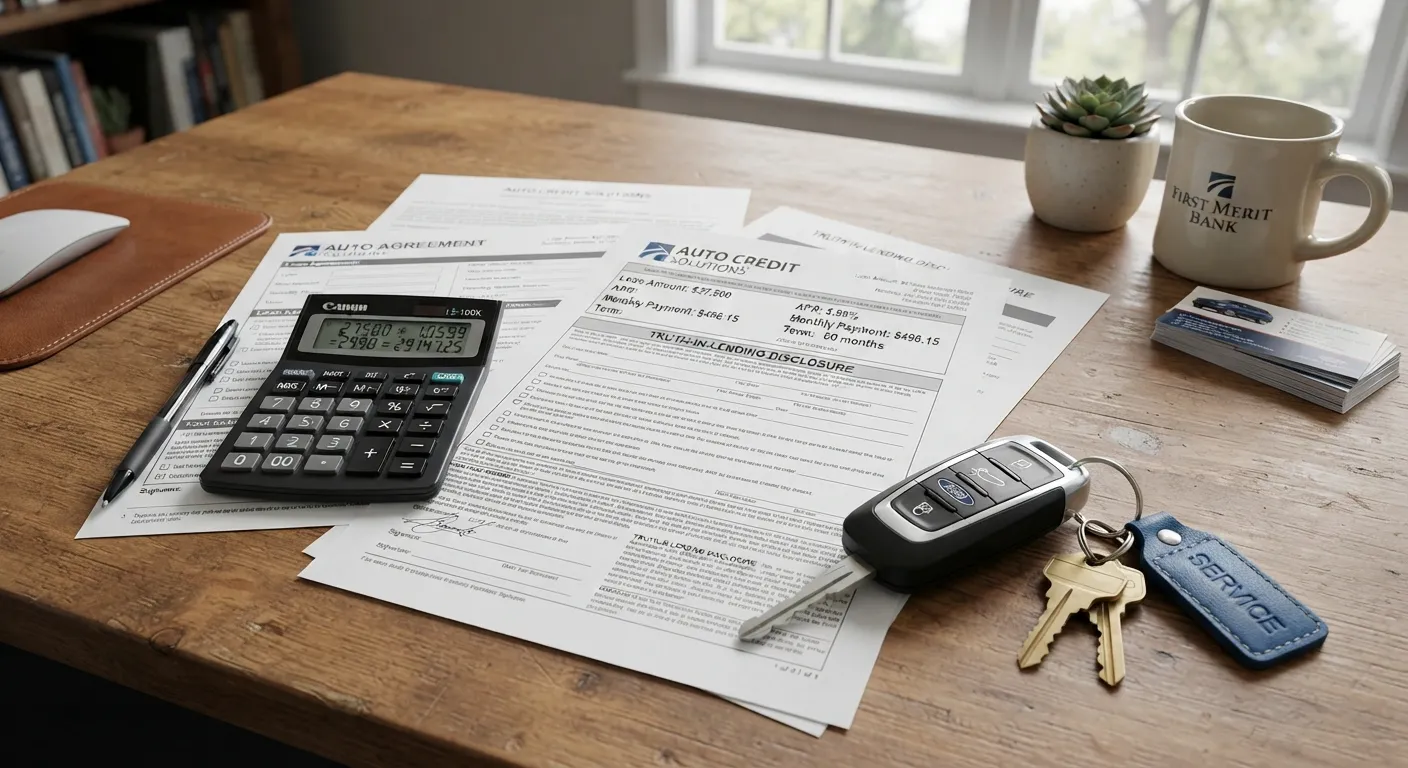
A credit score of 740 sits comfortably in the “very good” tier. Borrowers in this category normally qualify for the most competitive prime interest rates. A 16 percent car loan APR targets high-risk borrowers or individuals with damaged credit histories.
Salespeople insist high rates are standard practice. They mask dealership rate markups. Dealers inflate actual lender offers to secure larger profit margins at your expense.
The Hidden Trap of Long-Term Financing
Dealerships distract buyers with manageable monthly payments, such as $388 a month. They secretly stretch loan terms out to 72 or 84 months. Lower monthly obligations look attractive on paper. Carrying a 16 percent car loan APR over an extended period causes total interest payments to skyrocket. This severely damages your personal budget.
Safeguard your finances against predatory lending practices. Manage everyday expenses effectively. Read our insights on daily budget impulse spending and best business tools for entrepreneurs.
Smarter Alternatives to Dealership Financing
You never need to feel pressured into signing a bad financing agreement on the spot. Take control when a lender hands you an inflated rate:
- Secure External Pre-Approval: Visit a local credit union or online bank before visiting any dealership lot. Lock in a significantly lower auto loan rate.
- Leverage Competing Offers: Use external pre-approval as bargaining power. Force the dealership to lower their financing terms.
- Walk Away: Walk away when the numbers fail to make sense. Maintaining your current vehicle remains your smartest financial move until you secure a fair deal.
Disclaimer: The information provided on this website is for educational and informational purposes only and should not be construed as legal, tax, or financial advice.