Discovering that an old 401(k) balance from a previous employer has suddenly dropped to zero or been mysteriously “converted” causes immediate panic. Finding your retirement savings wiped out on a portal screen without prior notice usually points to institutional transfers, forced cash-outs of small balances, or administrative routing errors between payroll providers like ADP and major custodians like Fidelity. Furthermore, tracking down these missing funds requires a structured investigation into plan documentation and administrator transfer logs.
Navigating sudden balance discrepancies demands a clear understanding of retirement account portability regulations and federal rollover rules. Additionally, taking proactive steps ensures your accumulated savings are safely located and restored to an active account. Therefore, you should read our related guides on handling 401(k) accounts after a layoff or job change and navigating hidden retirement fund distributions. For official regulatory standards and plan compliance rules, consult resources from the U.S. Department of Labor and the Internal Revenue Service.
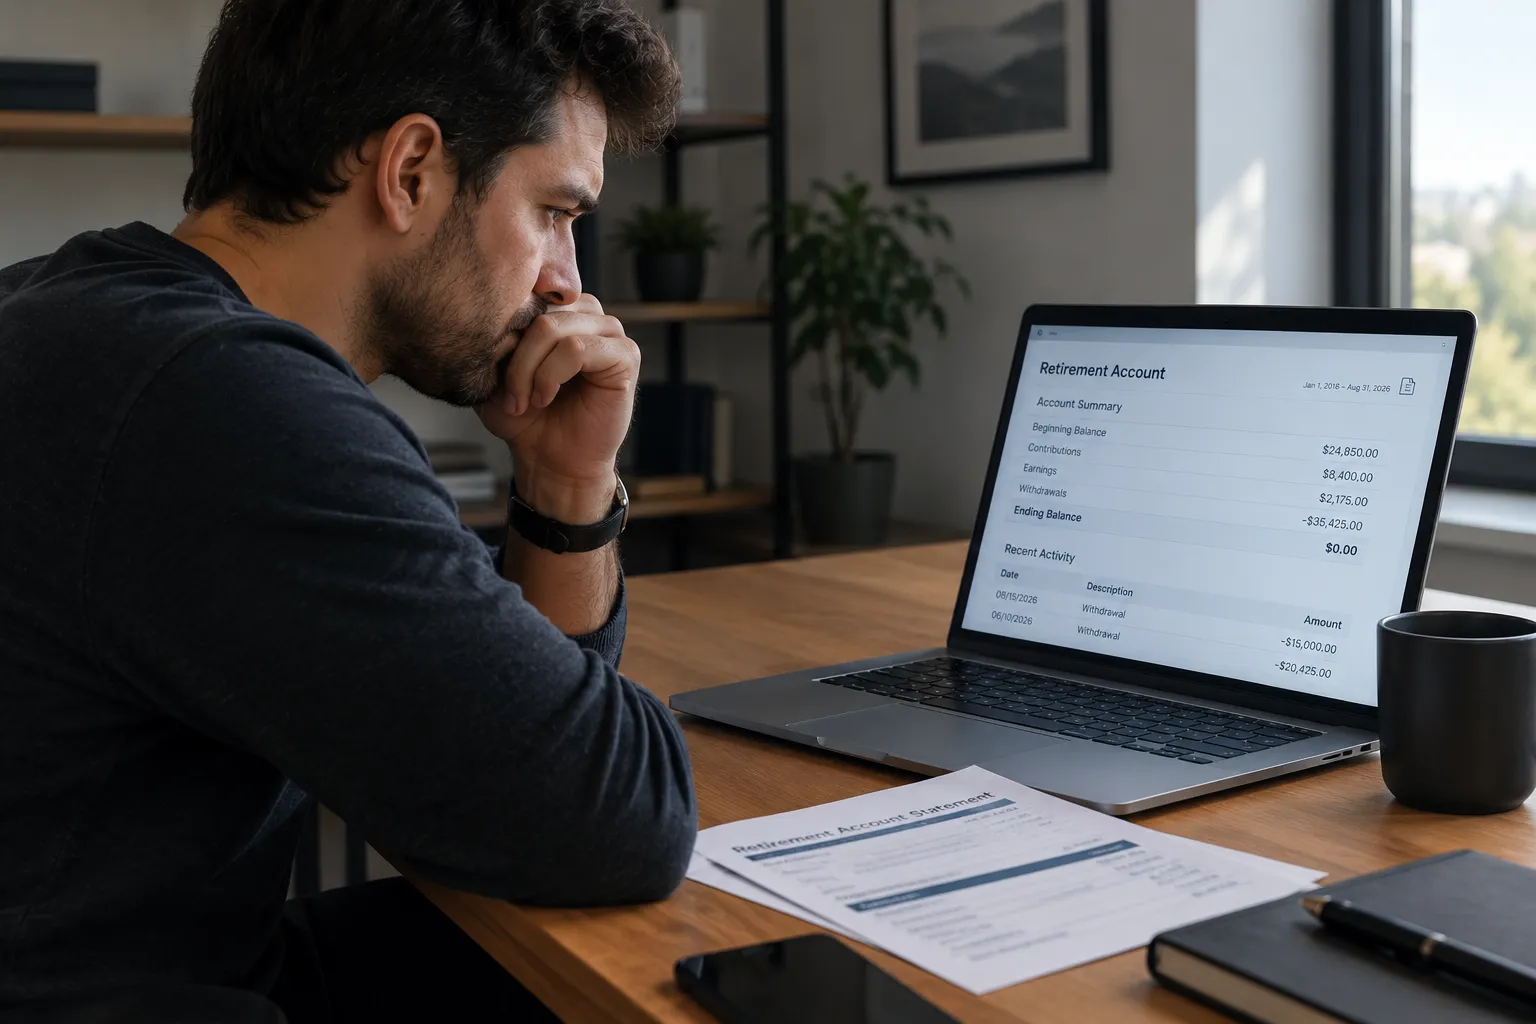
Why Does an Old 401(k) Balance Suddenly Show Zero?
When a retirement portal shows a zero balance after years of inactivity, it rarely means your money has vanished permanently. Instead, corporate plan sponsors frequently change recordkeepers—migrating assets from providers like ADP to firms like Fidelity or Empower. During these large-scale transitions, participant accounts can experience temporary visibility blackouts or require new login credentials to map old identifiers to the new platform.
Another common cause is a mandatory cash-out or rollover rule governed by IRS regulations. If your vested account balance falls below specific monetary thresholds (such as $1,000 or $5,000) after leaving a company, the plan sponsor has the legal right to transfer the money into an automatic Individual Retirement Account (IRA) institution on your behalf. Protecting your lifetime savings requires monitoring these transitions closely. Consequently, to learn more about workplace asset transitions and corporate consumer protections, review our articles on how to file a corporate consumer complaint and why financial and employment institutions track records.
Common Transfer Scenarios and Tracking Responsibilities
Pinpointing where your funds went requires understanding how payroll processors and financial custodians communicate asset transfers. When one institution claims they sent the balance elsewhere, you must establish an official paper trail across both entities.
| Transfer Situation | Primary Custodian Role | Action Required by Account Holder |
|---|---|---|
| Recordkeeper Migration | Migrate historical assets to a new platform (e.g., ADP to Fidelity). | Contact former employer’s HR department to request the specific transition confirmation number. |
| Involuntary Cash-Out IRA | Transfer sub-$5,000 balances into a designated default IRA institution. | Search state unclaimed property databases or use automated lost-account registries. |
| Processing Lag | Temporary ledger freeze during internal auditing or re-registration. | Obtain written statement of account status as of the exact date of the conversion. |
Data reference: According to Department of Labor (DOL) and IRS guidelines, plan administrators must maintain complete records of asset transfers and provide written notification before executing mandatory cash-outs or institutional migrations.
The Impact of Missing Retirement Assets on Long-Term Wealth
Losing track of even a modest 401(k) balance from an early job can severely disrupt your long-term financial security through lost compound interest. When accounts are closed, cashed out prematurely without your knowledge, or left idling in non-interest-bearing holding accounts, tax penalties and lost market growth drain your portfolio. Furthermore, recovering these funds ensures your retirement trajectory remains aligned with your original savings goals.
Employers and plan administrators are bound by fiduciary standards to safeguard participant assets. If an institution mishandles a rollover or loses track of converted balances during a transition, they bear the legal obligation to trace and restore the funds.
Step-by-Step Action Plan to Recover a Zero-Balance 401(k)
Resolving a mysterious zero balance requires methodically climbing the administrative ladder until you locate the exact custodian holding your assets. Establishing clear documentation prevents further bureaucratic delays.
- Contact the Former Employer’s HR Department: Request the name of the plan administrator, the specific corporate plan number, and documentation regarding any recordkeeper transitions.
- Demand Transfer Logs from the Originating Processor: If the initial provider (such as ADP) states funds were sent elsewhere, ask for the formal ACATS (Automated Customer Account Transfer Service) confirmation or check reference number.
- Search National Retirement Registries: Utilize secure databases like the National Registry of Unclaimed Retirement Benefits or state property registries if a forced cash-out occurred.
- File a Formal Complaint with EBSA: If custodians refuse to investigate or provide clear answers, escalate the issue through the Employee Benefits Security Administration (EBSA).
Navigating Fiduciary Violations and EBSA Oversight
When financial institutions lose track of retirement assets or fail to notify participants of major conversions, they violate federal fiduciary responsibilities under the Employee Retirement Income Security Act (ERISA). The Employee Benefits Security Administration, operating under the Department of Labor, actively investigates unauthorized balance liquidations and administrative negligence.
Filing an official inquiry triggers a compliance review of the plan’s handling procedures. Because financial institutions face severe federal penalties for failing to account for participant assets, formal oversight typically forces prompt cooperation and asset restoration.
Frequently Asked Questions
Is it legal for a 401(k) to show a zero balance without notice?
No, plan administrators are legally required to provide written notice prior to executing major account conversions, provider migrations, or involuntary cash-outs of small balances.
What should I do if my old provider claims they transferred my money to another custodian who has no record of it?
Request a formal written transfer confirmation detailing the exact date, destination routing numbers, and transaction tracking codes, then escalate the dispute to your former employer’s HR department.
Can an old 401(k) be cashed out automatically without my permission?
Under specific IRS rules, balances under $5,000 can be rolled over into a mandatory default IRA if you fail to respond to notices after leaving an employer, but funds cannot simply be absorbed or stolen.
How can I find lost retirement accounts from past jobs?
You can check past W-2 forms for plan numbers, contact former HR departments, or search specialized government and industry databases designed to locate abandoned retirement funds.
Disclaimer: The information provided on this website is for educational and informational purposes only and should not be construed as legal, tax, or financial advice.